Does Homeowners Insurance Cover Mold in Texas?
Sometimes, and usually only when the mold traces back to something the policy covers. That is the honest short answer for homeowners in Corpus Christi, TX and across the state. The details depend on your policy, your endorsements and the cause of the water, so treat this guide as a map of the questions to ask, not a coverage promise. It is not insurance or legal advice.
What the Texas Department of Insurance says. TDI's homeowners guide says most policies cover "Sudden and accidental release of water or smoke." Most don't cover "A continuous water leak; policies also won't cover mold removal, except to repair damage caused by a covered risk." TDI lists "mold removal" among the optional endorsements some policies offer. Many policies cap or exclude mold; check your declarations page.
Does homeowners insurance cover mold in Texas?
Read TDI's wording closely. A homeowners policy is built around covered causes of loss. If a covered event causes water damage, the policy may pay to repair that damage, and mold that results from it may be part of the claim, depending on the policy. If the mold grew from a problem the policy does not cover, such as a continuous leak, the mold usually is not covered either.
That is why the first question an adjuster asks is often "where did the water come from, and for how long?" The answer can matter more than how much mold there is.
Sudden and accidental vs. continuous leaks
The difference is about timing and cause, not size. A pipe that bursts and floods a hallway is the kind of event TDI describes as "sudden and accidental." A slow drip under a sink, an AC drain line that has leaked into a wall for months, or a roof leak that stained the ceiling over several seasons looks more like "a continuous water leak," which TDI says most policies don't cover. How your insurer classifies a specific loss depends on your policy language and the facts, so ask before you assume either way.
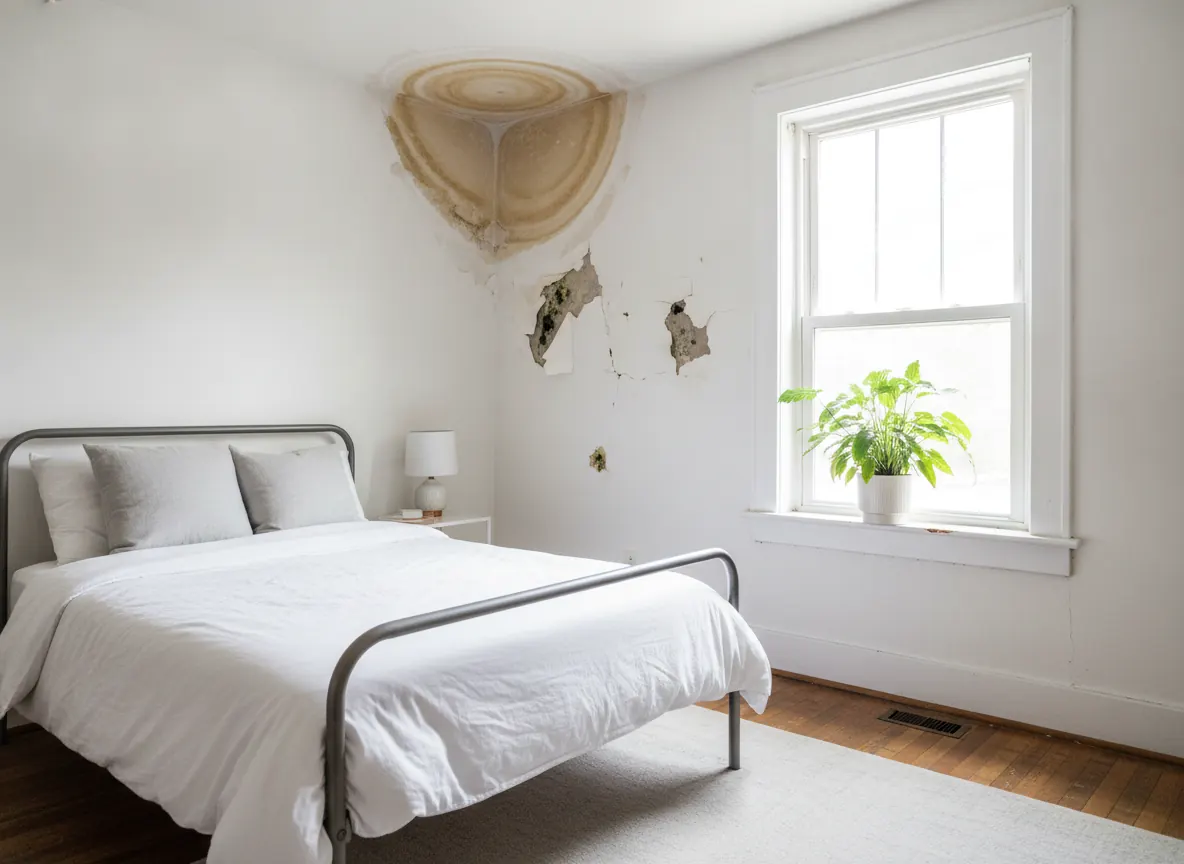
Practical takeaway: when you find a leak, stop it, write down the date, and take photos before anything is cleaned or torn out. A clear timeline helps whatever your policy says.
Is there a mold coverage cap in Texas?
No Texas statute setting a dollar cap on mold coverage was found in the research for this site. Caps, when they exist, come from the policy itself. Many policies cap or exclude mold; check your declarations page and any endorsements, and ask your agent what limit applies and whether a mold removal endorsement is available to you.
Wind, flood and mold on the Coastal Bend
On the coast, more than one policy can be involved. TDI says "If you live on the Texas coast ... your home policy might not cover wind and hail damage. The Texas Windstorm Insurance Association (TWIA) sells wind and hail coverage for coastal residents." TDI also notes that "TWIA won't sell you a policy if there's a hurricane in the Gulf," and that properties in 14 coastal counties are in a designated catastrophe area.
Flood is separate again. TDI: "Most home policies don't cover damage caused by floods," and "Most flood policies have a 30-day waiting period." Buying flood coverage after a storm forms is usually too late for that storm.
As a general rule, mold follows the cause. Which policy might respond depends on what let the water in. This table is a planning guide, not a coverage determination:
| What caused the water | Policy that may respond | What to check |
|---|---|---|
| Burst pipe or sudden appliance leak | Homeowners policy | Mold sub-limit or exclusion on the declarations page |
| Slow, continuous leak | Often none | TDI says most policies won't cover a continuous water leak |
| Wind-driven rain through storm roof or window damage | Wind coverage: TWIA or your home policy, depending on where your wind coverage sits | Your wind policy's terms for resulting water and mold |
| Rising water, storm surge or flooding | A separate flood policy, if you have one | Waiting period, and how the flood policy treats mold |
For storm-specific steps, see mold after a hurricane in Corpus Christi and the hurricane and flood mold page.
Will a past mold claim hurt my insurance later?
Texas has a specific protection here. Ask for the Certificate of Mold Damage Remediation (TDI form MDR-1). Insurers can't make underwriting decisions based on remediated mold damage when you have it (Ins. Code §544.303), and you must give buyers copies from the last five years (§1958.154(b)).
Section 544.303 applies when the property was remediated "as evidenced by a certificate of mold remediation" that establishes "with reasonable certainty that the underlying cause of the mold at the property has been remediated," or when an independent assessor or adjuster inspected and found no evidence of mold damage. The certificate does not guarantee insurance or a sale, but it is the document that law points to. On Texas jobs of 25 contiguous square feet or more, the licensed remediator must give it to you within 10 days of finishing.
How to document mold for an insurance claim
General advice that holds up whatever your policy says:
- Stop the water source if you safely can, and note the date and time you found it.
- Photograph the leak, the stains and any damaged belongings before cleanup. Wide shots and close-ups both help.
- Call your insurer or agent promptly and ask what they need, including whether they want to inspect before material is removed.
- Keep receipts for emergency drying, fans and any temporary repairs.
- On a 25+ square foot job, keep the licensed assessor's protocol, the remediator's work plan, the before-and-after photos and the clearance report.
- Keep the Certificate of Mold Damage Remediation with your house records.
Check both companies' licenses before work starts. Texas requires TDLR licenses for mold assessment and remediation work on 25 or more contiguous square feet (Occ. Code §1958.101–.102). Verify any company at tdlr.texas.gov/LicenseSearch. The TDLR license lookup guide walks through it.
If you end up paying out of pocket
Published national estimates, not quotes: Fixr (Aug 2025) lists $1,500–$9,000 for a typical job with an average near $3,500, and This Old House (Mar 2026) lists $1,200–$3,750 with an average near $2,300. A standalone mold inspection runs $450–$800 (Fixr, Jan 2025). The Corpus Christi mold remediation cost page breaks costs down by room and size. If you rent, your options run through your landlord and Texas Property Code chapter 92; see rental and landlord mold.
Frequently asked questions
Does homeowners insurance cover mold in Texas?
Sometimes. TDI says most policies cover sudden and accidental water releases but not a continuous water leak, and they won't cover mold removal except to repair damage caused by a covered risk. Many policies cap or exclude mold; check your declarations page and ask your agent.
Does flood insurance cover mold after a hurricane?
It depends on the flood policy's terms. TDI notes most home policies don't cover flood, so flood damage generally needs a separate flood policy, and most flood policies have a 30-day waiting period. Ask your flood insurer how it treats mold that follows covered flood damage.
Does TWIA cover mold?
TWIA sells wind and hail coverage for coastal Texas residents. Whether mold after wind damage is covered depends on the policy and the cause of the water. Read your TWIA or wind policy terms and ask the insurer directly; no one outside your insurer can promise coverage.
Will a mold claim raise my rates in Texas?
Texas Insurance Code §544.303 says an insurer may not make an underwriting decision on a residential policy based on previous mold damage or a mold claim if the property was remediated, as shown by a Certificate of Mold Damage Remediation, or was inspected and found free of mold damage. Keep that certificate.
Corpus Christi Mold Remediation is a free quote service, not a mold company. You describe the problem once, and independent mold inspection and remediation companies serving Corpus Christi and the Coastal Bend may reply with quotes. Companies may pay to receive requests, and they reply on their own schedules. Request free quotes or call (361) 247-3040.